

Credit Genie: Get Cash Advance
by Creditly Corp
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
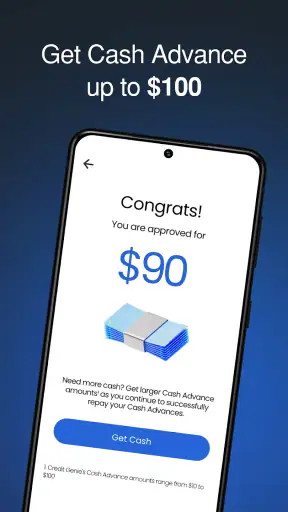
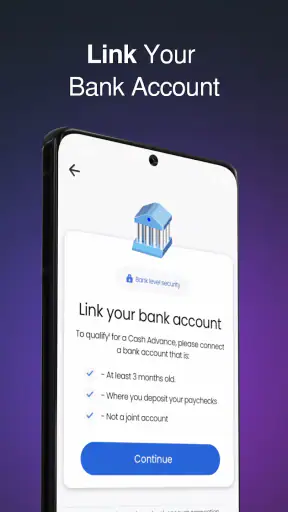
 Analysis by Getfullapps
I approached Credit Genie: Get Cash Advance as a finance app for moments when a regular payday is still ahead but an important expense cannot wait. Its focus is straightforward: help users explore access to cash through a mobile experience rather than beginning with a branch visit or a long desktop process. That makes it interesting for people who value speed and a phone-first workflow, but it also means the app deserves a careful look before anyone treats it as a complete answer to a money problem.
My review centers on something that is easy to overlook in finance software: whether the experience remains understandable and manageable for people using different devices, abilities, energy levels, and financial circumstances. A cash-advance product is not just about getting through screens. The wording, pace, visual hierarchy, and pressure around a decision can all affect whether a user makes a sensible choice.
How the app feels to read and navigate
Credit Genie is published by Creditly Corp and sits in the finance category. The app is free to install, carries an Everyone age rating, and has reached over a million installs. Those details tell me that it is aimed at a broad mobile audience, not a specialist group of financial professionals. In practice, that makes plain language and predictable navigation especially important.
The most useful way to approach the app is with a specific question already in mind: am I checking whether an advance may fit a short-term need, or am I looking for a general budgeting tool? I found that distinction important because a cash-advance service should not be confused with a full banking replacement. If I opened it while expecting detailed spending analysis, long-term savings planning, or the account controls of a traditional bank, I would be judging it against the wrong standard.
For readers who prefer a less crowded interface, a focused finance app can be easier than a banking app packed with transfers, cards, investments, alerts, and account menus. Fewer competing purposes can reduce the amount of searching required. That is a genuine advantage for someone who becomes overwhelmed by dense financial dashboards or who needs to complete one task quickly.
At the same time, clarity matters more here than it would in a casual shopping app. Before accepting any financial offer, I would slow down and read every explanation, eligibility message, repayment detail, and confirmation screen. A clean-looking interface can make a decision feel simpler than it really is. The app should be treated as a place to review an option, not as a reason to skip the review.
The current version is 3.4.1, and the app requires Android 10 or later. That operating-system requirement is worth considering for people using older phones, especially if the device is kept because it has a familiar layout, physical accessibility settings, or a screen that remains comfortable to read. A newer supported device may provide a smoother experience, but upgrading a phone is not a small accessibility adjustment for every household.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Reading financial information without rushing
My strongest practical advice is to read the app in stages. First, identify what the screen is asking you to do. Next, locate the amount, timing, and any conditions that affect the decision. Only after that should you continue. This workflow is more reliable than tapping the most prominent button and trying to reconstruct the details afterward.
That habit is particularly helpful for users with dyslexia, attention difficulties, limited financial confidence, or simply a stressful day. Short pauses between screens can prevent a confusing phrase from being mistaken for an approval, a request for information from being mistaken for a final result, or an estimate from being mistaken for guaranteed access.
I also recommend increasing the phone’s text size before beginning if small print is tiring. System-level display settings can help, but enlarged text may change how much content fits on a screen. If a sentence wraps awkwardly or a button moves, I would check the entire page rather than relying on the first visible line. In a finance app, missing a qualifier can matter more than saving a few seconds.
Users who depend on screen readers should test the main journey carefully rather than assuming that a simple visual layout is automatically easy to interpret aloud. Labels, reading order, focus movement, and the way warnings are announced can determine whether a person can complete the process independently. I cannot treat visual simplicity as proof of assistive-technology compatibility, so I would keep another trusted person available if the app does not expose an important message clearly.
Motor, visual, and sensory considerations
A phone-based application can be convenient for someone who cannot easily travel to a bank or handle paper forms, but convenience depends on the physical interaction. People with tremors, reduced dexterity, joint pain, or one-handed use may find repeated tapping, scrolling, typing, or holding a handset tiring. I would use a stable surface, enlarge the display where needed, and avoid completing a financial application while walking, commuting, or carrying something.
Voice input may reduce typing for some users, although it should be used thoughtfully around sensitive financial information. A quiet environment, careful review of dictated text, and a final visual or spoken check are sensible precautions. Automatic transcription can misunderstand names, addresses, or numbers, and a small error in a financial form can create unnecessary friction.
People with low vision may benefit from high-contrast system settings, display magnification, and a larger font. These tools can also create trade-offs: a page may require more scrolling, and content that was designed to appear together may be separated. I would not rely on color alone to understand whether a step succeeded or failed. If a message is unclear, I would look for its wording and context instead of interpreting a green or red visual cue by itself.
For users who are sensitive to motion, brightness, or notification interruptions, the best time to use the app is when the phone is calm and the surroundings are quiet. Finance decisions already require concentration. Removing background distractions makes it easier to distinguish an informational message from an action that changes the application process.
These considerations also apply to older adults. Someone may be perfectly comfortable using a smartphone but less comfortable with financial terminology, changing screen layouts, or a process that asks for several pieces of information in succession. I would recommend sitting beside the person and letting them control the phone, rather than taking over. That preserves their understanding and gives them a chance to stop when something does not make sense.
Using it in real-life situations
Consider a realistic example: I notice a necessary household expense two days before my normal income arrives. I open Credit Genie to see whether a cash advance could help, but I do not begin by entering information while distracted. I first write down the amount I actually need, check what bills are due after payday, and decide what repayment would do to the rest of the month. Then I use the app to investigate the option, reading each screen slowly and saving enough attention for the final terms.
That order matters. The app can support the search for a short-term solution, but it cannot decide whether borrowing will leave me short again later. If the expense is recurring, the better answer may be negotiating a bill, moving a payment date, using an existing emergency fund, or speaking with a bank or credit counselor. A cash advance may solve the immediate gap while creating another one if the underlying expense is larger than the next income cycle can comfortably absorb.
Situational access is one of the product’s clearest strengths. A phone is available in more places than a branch, and a user may be able to review an option privately at home. That can help people with mobility limitations, irregular work schedules, caregiving responsibilities, or anxiety around in-person financial conversations. It also helps someone who needs to begin a process outside traditional office hours, although I would still avoid making a rushed decision late at night.
Privacy creates a different situational concern. A person using a shared phone, public Wi-Fi, or a family device should think about who can see notifications, recent screens, or entered information. I would use a personal connection where possible, lock the phone afterward, and avoid asking the app to remember sensitive details on a device other people regularly use. These are practical habits, not guarantees, but they reduce avoidable exposure.
The free price removes an installation barrier, which is helpful for people who cannot justify paying upfront for a finance tool. It does not mean that every financial transaction or advance is cost-free. I would distinguish carefully between downloading the app and the financial terms presented during use. Anyone comparing options should judge the total obligation and timing, not the installation price.
Where it may still create barriers
The biggest barrier is not necessarily a button or a menu; it is the emotional pressure attached to urgent money. When a user is worried about rent, food, transport, or a medical expense, even readable screens can feel difficult to process. I would prefer to see every important condition presented in language that is easy to revisit, with no assumption that users will remember a previous screen. In practice, I would take notes before confirming anything.
Another limitation is that a mobile cash-advance app is not equally suitable for every financial situation. Someone with stable savings may find an emergency fund more flexible. Someone who needs a larger or longer-term amount may be better served by comparing a bank product, a credit union, or a structured personal loan. Someone trying to repair credit should not assume that using an advance service will produce the same outcome as a conventional credit-building product.
Users who cannot provide information through a phone, who have unreliable internet access, or who need face-to-face explanations may also find the format unsuitable. Likewise, a person who requires a support worker to interpret every financial term should not proceed alone simply because the app is easy to install. The right accessibility choice may be a different provider with a communication channel and assistance style that better matches their needs.
I would also avoid treating the app’s popularity as personal evidence that it is right for me. It has a 4.7 average from roughly seventy-eight thousand ratings, along with more than nine thousand written reviews, which suggests broad user engagement. Those figures are useful context, but they cannot tell me whether the product fits my income pattern, device, reading needs, or repayment capacity.
Comparing it with ordinary alternatives helps put the experience in perspective. A traditional banking app may offer a wider set of account tools and a clearer view of existing balances, while a branch may provide human explanation at the cost of travel and waiting. A budgeting app may be better for preventing the next shortfall, and a credit union or bank may be more appropriate when I need a planned borrowing arrangement. Credit Genie is most relevant when the immediate task is exploring a short-term cash option from a phone.
Who I would recommend it to
I would recommend trying Credit Genie to an adult who is comfortable using a smartphone, has a specific short-term need, and is prepared to inspect the financial details rather than accepting the first available path. It may be especially useful for someone who values a private, mobile-first starting point and finds broad banking apps too cluttered.
I would not recommend opening it with the assumption that approval is automatic, that an advance is free simply because the app is free, or that the service replaces budgeting. I would also steer away from using it repeatedly to cover ordinary living costs. Repeated shortfalls call for a wider plan, because an app designed for an immediate gap cannot by itself fix an income-and-expense mismatch.
For accessibility, my recommendation is conditional but practical: adjust the phone before starting, use a quiet setting, read each financial explanation completely, and stop if the content is not understandable. If the app’s interaction does not work with a user’s vision, dexterity, hearing, cognition, or communication needs, a different financial route is better than pushing through an unclear process.
My inclusive verdict
Credit Genie is a focused finance app from Creditly Corp that makes sense as a mobile starting point for people considering a cash advance. Its free installation, broad age rating, and phone-based format can lower practical barriers, particularly for users who cannot easily visit a branch. The large install base and strong average rating show that many people have chosen to use it, but I still see personal suitability and careful reading as more important than popularity.
My final view is balanced: the app is most useful when it supports a deliberate decision, not when it replaces one. I would use it in a calm setting, with the exact amount and repayment plan already considered, and I would compare the result with banking, budgeting, and non-borrowing alternatives. People with accessibility needs should test the complete journey on their own device and keep assistance available if any essential information is difficult to read, hear, operate, or understand.
That makes Credit Genie worth considering for a narrowly defined short-term situation, but not a universal financial solution. If the interface fits the way you read and use your phone, and the obligation fits comfortably into your next budget, it can be a convenient option to investigate. If either the access experience or the repayment plan feels uncertain, I would choose clarity and a different route before committing.
Pros
- User-friendly interface for easy navigation.
- Quick cash advances without hidden fees.
- Secure connection ensures data safety.
- Real-time notifications for cash updates.
- Flexible repayment options available.
Cons
- Requires access to personal banking info.
- Limited cash advance amounts for new users.
- Only available in certain regions.
- May impact user's credit score if misused.
- In-app ads can be intrusive for some users.
FAQs for Credit Genie: Get Cash Advance
What features does Credit Genie offer to users?
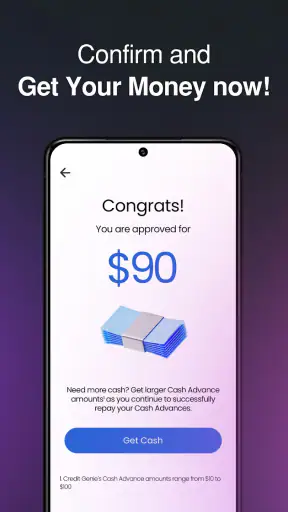
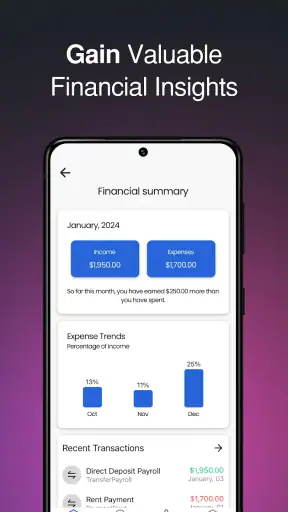
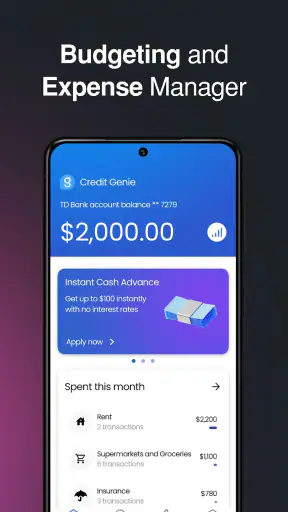
Credit Genie provides a variety of financial tools, including instant cash advances, budgeting assistance, and personalized financial advice. Users can easily manage their finances through the app, track spending, and receive timely insights to improve their financial health. The app also offers a secure platform for managing and monitoring transactions.
How does the cash advance feature work in Credit Genie?
Credit Genie's cash advance feature allows users to access a portion of their paycheck ahead of time. Users can request an advance, and the amount will be directly transferred to their bank account. The app ensures a hassle-free repayment process by automatically deducting the advance on the next payday, avoiding any hidden fees or interest.
Is Credit Genie safe to use for managing finances?
Yes, Credit Genie prioritizes user security by employing advanced encryption methods to protect personal and financial data. The app complies with industry standards and regulations to ensure user information remains confidential and secure. Regular updates and security audits are conducted to maintain high security standards.
Are there any fees associated with using Credit Genie?
Credit Genie does not charge interest on cash advances. However, there may be a small fee for using certain features within the app. It is advisable for users to review the terms and conditions and any associated costs before utilizing specific services. Transparency is a key aspect of Credit Genie's user experience.
Can Credit Genie help improve my credit score?
While Credit Genie primarily focuses on cash advances and budgeting, it also provides insights and tips on managing credit health. By using the app to track expenses and ensure timely repayments, users can potentially improve their financial behavior, which may positively impact their credit score over time.

Credit Genie: Get Cash Advance
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@creditgenie.zendesk.com, visit https://creditgenie.com, or review their https://www.creditgenie.com/privacy-policy.










